Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.8% HIKE
IMPLIED CHANGE +7.2 bps
12-MONTH OUTLOOK +78.7 bps 3-4 HIKES
TARGET BAND 3.75 - 4.00%
SOFR 3.88%
LATEST FED UPDATE 10/6/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
People lined up outside a bank entrance in a grand city building

Reading the Panic: How Investors Perceived Bank Risk During the 2023 Bank Run

Natalia Fischl-Lanzoni, Martin Hiti, and Asani Sarkar The bank run that started in March 2023 in the U.S. occurred at an unusually rapid pace, suggesting that depositors were surprised by…
The Financial Stability Implications of Tokenized Investment Funds

The Financial Stability Implications of Tokenized Investment Funds

Pablo Azar, Francesca Carapella, JP Perez-Sangimino, Nathan Swem, and Alexandros P. Vardoulakis In a previous post, we provided background information about the emergence of tokenized investment funds and their use…
The Emergence of Tokenized Investment Funds and Their Use Cases

The Emergence of Tokenized Investment Funds and Their Use Cases

Pablo Azar, Francesca Carapella, JP Perez-Sangimino, Nathan Swem, and Alexandros P. Vardoulakis A blockchain is a distributed database where independent computers across the world maintain identical copies of a transaction record, updating…
Financial Intermediaries and Pressures on International Capital Flows

Financial Intermediaries and Pressures on International Capital Flows

Linda S. Goldberg and Samantha Hirschhorn Global factors, like monetary policy rates from advanced economies and risk conditions, drive fluctuations in volumes of international capital flows and put pressure on…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
What is a Semi-Custom Home? How it Differs From Custom and Spec Homes

What is a Semi-Custom Home? How it Differs From Custom and Spec Homes

A white house with a pathway leading up to the front door. The owner might be wondering whether they should sell to an iBuyer.

If you’re looking for a new construction home, you may come across terms like semi-custom, custom, and spec home. While all three involve new construction, the amount of choice you have over the home’s design, finishes, layout, and features can vary significantly. A semi-custom home gives buyers some flexibility to personalize a builder’s existing plans, […]

The post What is a Semi-Custom Home? How it Differs From Custom and Spec Homes appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.

Read More »
What is a New Construction Home?

What is a New Construction Home?

A new construction home is a property that is newly built or still being built and has not previously been occupied as a residence. Buyers may purchase a new construction home before construction begins, while it is under construction, or after it is completed. The term “new home” can be broader. A home can be […]

The post What is a New Construction Home? appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.

Read More »
Mortgage industry professionals posing together at a business event

Verification, U/W, PPE, Margin Mgt. Tools; Webinars; MISMO and FRAME Offer; Buydown breakdown

We’re waist deep in conferences (click here to view or add events), and every week I receive a half a dozen invitations to mortgage golf events centered around a conference. How about coming up with something where you can see and talk to more than three other people for 3-4 hours? Group hikes? Make-a-bear? Mini-golf? Bowling? Croquet? Pretzel making? Axe throwing? Perhaps we’ll see companies and state organizations shift their fund raising away from golf outings toward pickleball and bocce ball. Are President’s Award trips on their way out? There is no doubt that we should all celebrate successes. But does anyone ask the top (fill in the blank) what they would like? There seems to be a growing opinion that, “Maybe our top crew doesn’t want to go on vacation with co-workers, so let’s give them some extra vacation so they can spend it with their families.” In the past, some companies (Wells Fargo correspondent jumps to mind) would have awards trips for their ops staff. That is a fine idea. (Today’s podcast can be found here. This week’s ‘casts are presented by Gateless, intelligent Automation that gives you the competitive edge. Gateless solutions reduce costs, deliver a superior borrower experience, and mitigate risk by automating tasks and decisions historically made by people. Today’s has an interview with Falcon Capital Partners’ Sam Valverde on the general importance of the bond market, an analysis of recent rate hikes, future fixed-income projections, and the potential downstream risks to the housing market.)

Read More »
Another Red Start, And It's Not All About Oil

Another Red Start, And It’s Not All About Oil

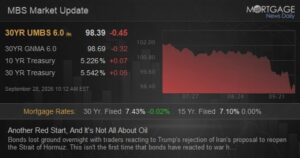
Bonds lost ground overnight with traders reacting to Trump’s rejection of Iran’s proposal to reopen the Strait of Hormuz. This isn’t the first time that bonds have reacted to war headlines regardless of movement in oil prices. While oil also moved higher throughout the overnight session, bonds are increasingly detached in the bigger picture with yields staying relatively higher as they wait for a substantive change in the war or the economy. For all of the drama and volatility, it’s really that simple.

Read More »
Flood-damaged urban street with collapsed roadway and debris between buildings

Who’s Borrowing and Lending in Repo Markets?

Repo markets play a vital role in the U.S. financial system. In this three-part series, we examine who participates in these markets, what trade-offs influence how different repo segments are structured, and why repos matter for monetary policy. Today’s post introduces repo transactions, focusing on the major private-sector participants and why they engage in these markets.

Read More »
Mortgage-backed securities recovery chart with rising arrow and bear trap imagery

Respectable Recovery. Is It a Trap?

Respectable Recovery. Is It a Trap?

First thing’s first: the parabolic flourish of bond selling of the past 2 weeks is arguably unprecedented in recent memory. Specifically, we’ve seen similar levels of overall weakness over similar time frames, but we haven’t seen the same sort of concentrated acceleration of selling at the tail end of a months-long selling trend. The only remotely comparable precedent was late September 2023 when a Fed dot plot surprised the market with a higher rate outlook followed by 2 weeks of stronger-than-expected econ data. There was a decent recovery on several occasions on the way up, but a sustainable recovery didn’t start until early November. Throughout that process, it was data that set the tone. With that in mind, we’re heading into a week with big-ticket data and we expect bonds to take cues accordingly. Of course oil and war headlines continue to matter as well. While today’s recovery was “nice,” it doesn’t make any guarantees about where we’ll end up next week. That said, it very well could indicate that bonds have sold as much as they need to sell unless next week’s data/events add additional provocation. 

Econ Data / Events

Core CapEx (Aug)

1.6% vs 0.5% f’cast, 0.2% prev

Durable goods (Aug)

0% vs -0.4% f’cast, 1.1% prev

Consumer Sentiment (Sep)

48.1 vs 47.6 f’cast, 51.7 prev

Sentiment: 1y Inflation (Sep)

4.6% vs 4.6% f’cast, 4% prev

Sentiment: 5y Inflation (Sep)

3.4% vs 3.4% f’cast, 3.3% prev

U Mich conditions (Sep)

50.9 vs 49.5 f’cast, 51.9 prev

Market Movement Recap

08:54 AM MBS up nearly a quarter point and 10yr down 1.9bps at 5.182

12:06 PM Rallying on war headlines. 10yr down 3.1bps at 5.169. MBS up 11 ticks (.34).

03:20 PM Best levels.  MBS up more than 5/8ths and 10yr down 3.7bps at 5.164

Read More »
New home sales return to typical range after unusually large bounce

New Home Sales Back in The Range After Uncommonly Big Bounce

The new home market returned to the longer-term range last month, with sales seeing their 4th biggest rebound in 4 years.  Sales of new single-family homes rose to a seasonally adjusted annual rate of 684,000 in August, up 6.4% from July’s revised 643,000 but 2.0% below the same month last year. The increase puts sales back above the 600,000 mark after July’s pullback, although the broader trend remains relatively flat. The number of new houses for sale was virtually unchanged at 483,000 , down 2.0% from a year earlier. With sales picking up while inventory held steady, the implied supply fell to 8.5 months , down from 9.0 months in July and essentially unchanged from August 2025. Pricing was mixed, the median sales price edged up to $393,700 , a 0.4% increase from July but 5.8% below August 2025. The average sales price fell to $478,700 , down 9.1% from July and 8.8% from a year earlier. As a reminder, price movements in this data set are not necessarily apples to apples as they don’t adjust for changes in square footage, neighborhood, etc.
Sales (MoM): +6.4%
Sales (YoY): -2.0%
Inventory (MoM): 0.0%
Inventory (YoY): -2.0%
Months’ Supply: 8.5 (down from 9.0 prior month; 8.5 YoY)
Median Price: $393,700
Average Price: $478,700

Read More »
Approved mortgage application illustrating stronger refinance demand as home purchases stall

Refi Demand Logically Lower While Purchases Grind Sideways

Mortgage demand remained subdued last week as the 30-year fixed rate climbed above 7%. The Mortgage Bankers Association (MBA) reported a 1.5% decline in total mortgage application volume for the week ending September 18, following a 4.1% drop the week before.  Purchase activity was the only saving grace. While technically 1% lower week-over-week, it has generally been moving sideways for the past few weeks.  Refinance demand was more sluggish. The Refinance Index declined another 3% and was 62% lower than a year earlier. MBA said the pace of refinancing has now reached its slowest level since February 2025 , a reflection of how few existing borrowers can benefit from replacing their current mortgage with one carrying today’s higher rate. “Mortgage rates vaulted higher last week, with the 30-year fixed rate at 7.12 percent – the highest level since May 2024,” said Mike Fratantoni, MBA’s SVP and Chief Economist. He added that the higher fixed rates prompted more borrowers to consider adjustable-rate mortgages, even as both purchase and refinance applications continued to decline. The shift toward ARMs was one of the more notable developments in the latest data. ARMs accounted for 9.8% of application volume, up from 8.4% the week before. The average rate for a 5/1 ARM fell to 6.10%, putting it more than a full percentage point below the 30-year fixed rate. That spread is large enough to make the adjustable option more noticeable to borrowers facing 7% or higher fixed rates.

Read More »
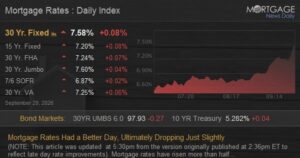
Mortgage rates daily index showing 30-year fixed rate at 7.58%

Mortgage Rates Had a Better Day, Ultimately Dropping Just Slightly

(NOTE: This article was updated  at 5:30pm from the version originally published at 2:36pm ET to reflect late day rate improvements). Mortgage rates have risen more than half a point in 2 weeks. While that’s certainly not the fastest jump we’ve seen, it is an extraordinarily uncommon pace–happening less than once per year on average (i.e. it only happened 3 times between 2010 and 2019). Today’s initial increase was modest in the bigger picture, adding only 0.04% to yesterday’s levels and leaving the average top-tier 30yr fixed rate still just a hair below 7.50%. This is roughly in line with the highs from early 2024 and still well below the highs of 8% seen in October 2023. Much of that initial 0.04% increase can be thought of as a hangover from yesterday’s volatility. In fact, the underlying bond market had already improved day-over-day at the time we marked the 0.04% increase. Thankfully, additional gains in the afternoon led lenders to drop rates back below yesterday’s latest levels. The final mark was 7.43% for the average lender. [thirtyyearmortgagerates] Whether this friendly bounce means anything about the road ahead is a different matter. If traders knew what the road ahead looked like with any certainty, they wouldn’t sit on their hands and lose money between now and then. In other words, anything that you or I can conclude about the near-term future is already priced-in to current levels. The next leg higher or lower for rates will likely be determined by a combination of economic data that hasn’t come out yet and war-related headlines that could either help or hurt the fuel price outlook. Next week is a big week for econ data and every week brings new potential for oil price fluctuations these days. In addition, the month/quarter end trading environment increases the risk of volatility regardless of directional cues from data/events.

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy