


‘Lawfare is now the norm’: MLS leaders brace for more legal battles
MLS legal experts at CMLS Open House urged scenario planning around cooperation, participation, and data access as lawsuits and demand letters increase

MLS legal experts at CMLS Open House urged scenario planning around cooperation, participation, and data access as lawsuits and demand letters increase
Mortgage demand shocked no one by declining last week as mortgage rates climbed to their highest level in nearly three years. The Mortgage Bankers Association (MBA) reported a 6% drop in total mortgage application volume for the week ending September 25. Both sides of the market moved lower, with the seasonally adjusted Purchase Index falling 4% and refinance applications dropping 9% . MBA said purchase and refinance activity both reached their slowest weekly pace since 2025 . Refinances always get hit hardest by rate spikes with the index now 56% lower than a year earlier. Government refinance applications fell 13% from the prior week. “Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. He noted that the 30-year fixed rate reached 7.30%, its highest level since November 2023. There was another sign that some borrowers are looking for alternatives to the traditional fixed-rate mortgage. ARM loans accounted for 10.3% of all applications, the highest share since October 2025. Kan said ARM rates were roughly 80 basis points below fixed rates, although the average 5/1 ARM rate also moved higher in the latest survey. Mortgage Rate Summary:
30yr Fixed: 7.30% (from 7.12%) | Points: 0.75 (from 0.73)
15yr Fixed: 6.56% (from 6.43%) | Points: 1.02 (from 1.15)
Jumbo 30yr: 7.27% (from 7.15%) | Points: 0.50 (from 0.53)
FHA: 6.97% (from 6.78%) | Points: 1.18 (from 0.96)
5/1 ARM: 6.47% (from 6.10%) | Points: 1.20 (from 0.76)
Home prices picked up a little more speed in July, as both FHFA and the S&P Cotality Case-Shiller Home Price Indices showed stronger annual appreciation than in their previous readings. The gains remain relatively modest by historical standards, and while nominal prices are still moving higher nationally, the picture looks considerably less impressive after accounting for inflation. The FHFA House Price Index rose 0.3% from June to July, bringing the annual increase to 2.6% . While the national market is still technically appreciating, there’s more and more variation between different metro areas with some holding steady or even contracting. Case-Shiller tells a similar story, though its national measure is running at a somewhat slower pace. The U.S. National Home Price Index rose 1.9% year over year in July, up from 1.6% in June. The 10-City Composite increased 3.4% , while the 20-City Composite was up 2.5% . The annual price appreciation chart shows a nice little uptick, but the takeaway is tempered in inflation-adjusted terms. Both of the big U.S. inflation reports showed annual changes of 3.4% last month, and even higher in July (the month that lines up with these home price reports). Any way you slice it, that means home prices aren’t keeping pace with broader inflation. Whether or not that’s a bad thing is another story. Some would say it wouldn’t be the end of the world for prices to merely hold steady and allow income growth to slowly chip away at affordability.
Student-athletes receive mentoring and complete requirements to become licensed real estate referral agents
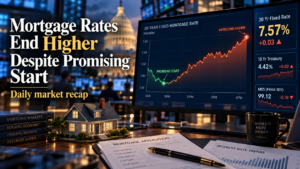
Mortgage rates rose 0.04% today to an index value of 7.57% for a top-tier 30yr fixed scenario for the average lender today. That uptick in and of itself isn’t especially large, but it’s a bit counterintuitive on a day where the hotly anticipated jobs report came in much weaker than expected. The jobs report has 2 key components: Nonfarm Payrolls (NFP) and the unemployment rate. For most of the time any rate watcher can remember, NFP matters way more. The market still reacts to it (which is why bonds initially improved this morning), but unemployment has arguably taken the lead in terms of accurately capturing labor market trends. Even then, today’s unemployment rate of 4.2% (up from 4.1% last month) shouldn’t have been a problem. The catch was that the unrounded numbers made the gap even smaller (4.175% vs 4.141%). Additionally, more people entered the labor force. If the labor force had held steady with last month, today’s unemployment rate would have been 3.951%. None of those numbers is particularly troubling for the employment outlook, but 3.951% especially so. That helped explain why bonds eventually gave back their early gains, along with a rebound in oil prices and easing concerns about European bond markets that had helped U.S. rates move lower yesterday. When bond gains evaporate, mortgage lenders may be forced to raise rates during the day. This happened on multiple occasions. The average lender was actually slightly lower at first, but ultimately ended higher compared to Thursday’s latest levels.
The operational signals that show strain before the leaderboard does
Rising prices alongside weaker sales and closed listing ecosystems are reducing consumer visibility and competition
September endorsements dropped to 1,790 — the lowest figure since April 2020 — while HMBS issuance fell to $446 million
A jobs miss sent the 10-year yield to as low as 5.17% before yields rose higher toward 5.28%