


CRMLS moves first, asking court to block Compass antitrust claims
The MLS asks a New York federal judge to declare its policies procompetitive and antitrust compliant

The MLS asks a New York federal judge to declare its policies procompetitive and antitrust compliant
The Federal Home Loan Banks’ Mortgage Partnership Finance® Program helps community lenders expand homeownership through liquidity, collaboration and targeted financing solutions
The new appraisal standard is more than a form update: Five actions can help lenders protect pipeline continuity and capture the benefits of better-structured collateral data
The Fed lifted the target range by 25 bps to 3.75%–4%, but mortgage rates track long-term yields, not the Fed funds rate
A majority of shareholders backed the removal of five directors, including interim CEO Daniel Lewis, with Better finalizing his successor
Bipartisan Build America Caucus sketches housing reform targeting zoning, building material costs and inefficient financing barriers
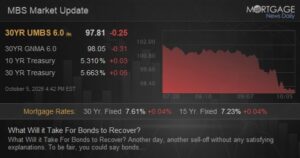
What Will it Take For Bonds to Recover?
Another day, another sell-off without any satisfying explanations. To be fair, you could say bonds just traded the curve today with anything 3yrs or shorter rallying at the expense of the longer end of the curve. But for the mortgage market, <3yrs is too short-term to matter. Data and headlines did not line up well at all with the weakness, so take your pick from the general themes we’ve added to the daily lock/float considerations. At some point, yields will have moved high enough to motivate investors to buy bonds for investment purpose (as opposed to tactical or compulsory trading purposes). Until then, the trend is not your friend.
Econ Data / Events
ISM Biz Activity (Sep)
56.5 vs — f’cast, 61.7 prev
ISM N-Mfg PMI (Sep)
54.9 vs 55 f’cast, 55.4 prev
ISM Services Employment (Sep)
50.1 vs — f’cast, 47.8 prev
ISM Services New Orders (Sep)
59.8 vs — f’cast, 60.9 prev
ISM Services Prices (Sep)
74.0 vs — f’cast, 72.6 prev
Market Movement Recap
10:07 AM Modestly weaker at the open, but holding ground after ISM. 10yr up 1.7bps at 5.296. MBS down 1 tick (.03).
12:51 PM weakest levels. no new reasons. MBS down 10 ticks (.31) and 10yr up 5.5bps at 5.334
04:01 PM Off the weakest levels, but again, not for any particular reason. MBS down a quarter point and 10yr up 3bps at 5.309
Dennis succeeds Patrick Bain, who is stepping down after 16 years with the company
Anil Hinduja’s employment with Freddie Mac ended Oct. 1