


Mortgage Banking Summit: ‘Street fight’ market concentrates growth toward nondelegated lenders
Data shows a small fraction of lenders capturing most new production as LOs shift to brokerage and correspondent platforms

Data shows a small fraction of lenders capturing most new production as LOs shift to brokerage and correspondent platforms
New team additions posted $180 million in the past 12 months, the RealTrends Verified brokerage reported
“A clear conscience is usually the sign of a bad memory.” How’s your memory of rates, and what you did when they moved higher? 30-year mortgage rates were about at this level, briefly, exactly three years ago, but before that we weren’t here since the late 1990’s when they were at these levels for a long time. How many of your sales staff were in the biz then? As the United States’ deficit continues to increase, 5-year Treasury securities, issued at 1 percent, are paying off and the U.S. Government is now having to pay 5 percent on new 5-year T-notes. At the Virginia Mortgage Bankers Association’s Conference, which wraps up today, the talk on the stage and in the hallways revolved around this relatively high rate environment, AI, credit changes, LOs being relevant, and how lenders should pay attention to demographics. Along those lines, the VantageScore news this week will certainly be a topic on Last Word today at 10AM PT when Brian Vieaux, Tracey King, Kevin Peranio, and Christy Soukhamneut discuss changes in credit, AI governance, the UAD 3.6 shift, and industry storylines. (Today’s podcast can be found here. This week’s ‘casts are presented by Gateless, intelligent automation that gives you the competitive edge. Gateless solutions reduce costs, deliver a superior borrower experience, and mitigate risk by automating tasks and decisions historically made by people. Today’s has an interview with Eris Future’s Geoffrey Sharp on how futures contracts replicate the cash flows and functionality of over-the-counter interest rate swaps, and are suitable for short-term trading or long-term hedging.)
Lenders can begin sending FHA appraisals in UAD 3.6
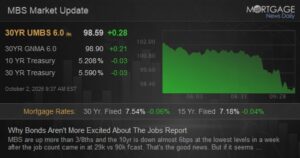
MBS are up more than 3/8ths and the 10yr is down almost 6bps at the lowest levels in a week after the job count came in at 29k vs 90k f’cast. That’s the good news. But if it seems like the rally should be bigger for such a hotly anticipated report, there’s a reason. First off, we need to remember that it takes fewer jobs created to keep unemployment stable these days. Even the Fed has said to focus more un the unemployment rate. In today’s case, it only rose to 4.175% from 4.141% last month. Moreover, it did so despite the participation rate rising 0.2%. In other words, had it not been for that 0.2% uptick in participation, Unemployment would have come in at 3.951%. Bottom line: this report wasn’t really weaker than expected apart from wage growth. The market just hasn’t figured out how to forecast NFP in a low-growth labor force.
The requirement is expected to take effect one to three months after it is announced, per Bloomberg
In the role, Kaminski will lead strategy and operations for Teravalis, a 37,000-acre master planned community in Buckeye
Thursday’s Rally Sets Up For a Very Interesting Friday
Of course we had to have a big, interesting move in the bond market on the day before an economic report also famous for causing big, interesting moves. On such occasions, if Friday delivers on “interesting” it will either negate today’s bullishness or add to it in a way that makes today retroactively look like an obvious near-term top in rates. There’s no way to know enough about today’s rally to conclude that–let alone the unknowable results of the jobs report and the ensuing reaction. All we know: today was a win. If more wins follow, we can talk more about bigger picture supportive ceilings.
Econ Data / Events
Continued Claims (Sep)/19
1,701K vs 1730K f’cast, 1719K prev
Jobless Claims (Sep)/26
197K vs 200K f’cast, 197K prev
Market Movement Recap
09:04 AM Another round of 8:20am selling erases small overnight gains. 10yr up 1.6bps at 5.303 and MBS up 3 ticks (.09).
01:05 PM Big intraday reversal (in a good way). European credit spreads could be a factor as well as short-covering ahead of jobs report and new-month trading. MBS up 3/8ths and 10yr down 7bps at 5.218
Summit participants question how investors will treat VS4-driven MBS pools