
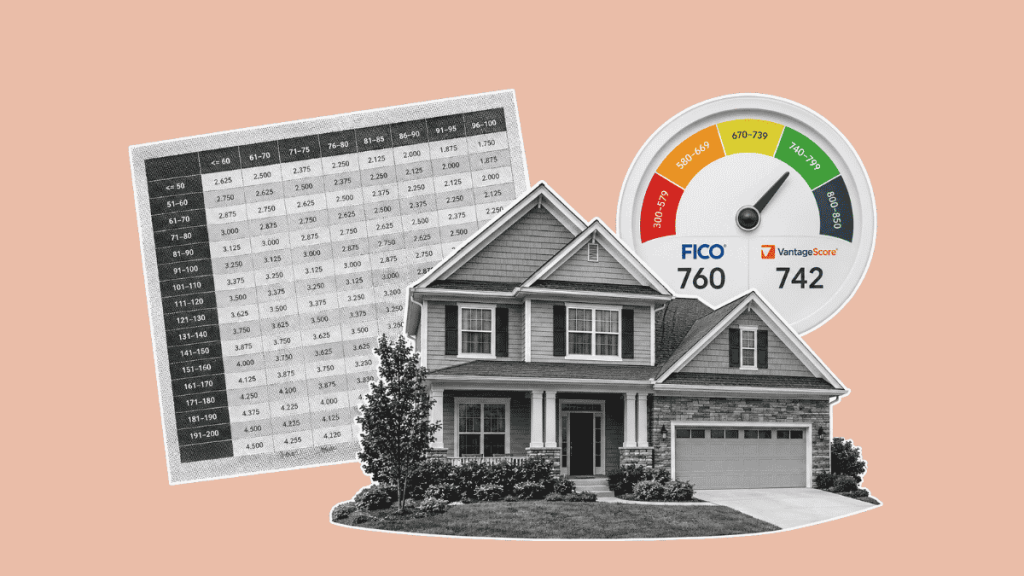


FHFA says Fannie, Freddie will use one LLPA grid for FICO and VantageScore
Change follows lender feedback after VantageScore 4.0 was approved for eligible conventional loans earlier this month

Change follows lender feedback after VantageScore 4.0 was approved for eligible conventional loans earlier this month

Mortgage rates are volatile, prices are high, but supply is rising – a mixed bag for homebuyers. So, is now a good time to buy a house?
The post Is Now a Good Time to Buy a House? appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
Mortgage rates moved higher again on Tuesday as the bond market continues recalibrating expectations for Fed policy, economic growth, and inflation. The weakness is especially frustrating considering a fairly large drop in oil prices today, but as we discussed yesterday, rates have a lot more on their mind than oil these days. Our top-tier 30yr fixed rate index rose from 7.50 to 7.58% today–the highest since November 1st, 2023. In this sense, mortgage rates are doing much better than their often-cited benchmark, the 10yr Treasury yield, which is the highest level since 2007. That’s because mortgage rates are directly based on mortgage-backed securities (MBS) and not U.S. Treasuries, and MBS have been outperforming Treasuries relative to 2023’s levels. Today’s economic data didn’t offer meaningful relief although it wasn’t a driver of today’s upward pressure. We’re seeing more and more evidence that at least some of that pressure has to do with factors such as the quarter-end trading environment which transcends news headlines and economic reports. This doesn’t necessarily mean that rate momentum will reverse on October 1st, but the month could at least restore a more logical relationship between typical causes and effects.
NRMLA President Steve Irwin said the trade group will continue to lobby HUD, FHA on lowering the upfront mortgage insurance premium for federally insured reverse mortgages
Seattle recorded the largest annual decline for the second consecutive month
This checklist prioritizes relationship reactivation, one monthly process improvement and consistent publishing that stays useful instead of promotional
The move adds about $325M in annual production and expands the company’s presence in Tennessee and Missouri
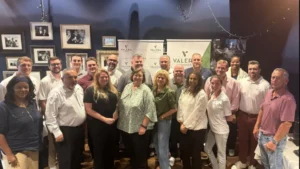
Valera Homes, a sister of StoneManor Homes, launches with four communities, targeting first-time, value-conscious buyers
ORRA data shows 53% of buyers are shopping at lower price points, while the 30-year fixed moved above 7%