

Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.4% HIKE
IMPLIED CHANGE +7.1 bps
12-MONTH OUTLOOK +83.0 bps 3-4 HIKES
TARGET BAND 3.75 - 4.00%
SOFR 3.89%
LATEST FED UPDATE 10/6/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
Does the Phillips Curve Steepen When Costs Surge?

Does the Phillips Curve Steepen When Costs Surge?

Simone Lenzu Inflation does not always respond to cost and demand pressures in the same way. When shocks are small, the mapping from costs to prices is roughly proportional—double the…
Anatomy (not Autopsy) of the Phillips Curve

Anatomy (not Autopsy) of the Phillips Curve

Simone Lenzu The relationship between inflation and real economic activity has long been central to debates in macroeconomics and monetary policy. At the core of this debate is the Phillips…
New York Fed EHIs Reveal Small Business Struggles

New York Fed EHIs Reveal Small Business Struggles

Will Aarons and Asani Sarkar The New York Fed’s Economic Heterogeneity Indicators (EHIs) aim to study macroeconomic outcomes experienced by various groups of people and businesses. We recently added a suite of indicators describing the performance…
A New Dataset for Consumer Spending in the New York Fed EHIs

A New Dataset for Consumer Spending in the New York Fed EHIs

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy We are enhancing our set of Economic Heterogeneity Indicators (EHIs) by adding a set of metrics on consumer spending with…
Understating Rising Quality Means Import Price Inflation Is Overstated

Understating Rising Quality Means Import Price Inflation Is Overstated

Danial Lashkari It is common for price measures to consider changes in quality. That is, a price index might fall even though listed prices are unchanged because the quality of…
Disability in the Labor Market: Earnings

Disability in the Labor Market: Earnings

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy In our previous post we learned that, in general, people with disabilities participate in the labor market at significantly lower…
Disability in the Labor Market: Employment and Participation

Disability in the Labor Market: Employment and Participation

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy Among people in prime working age (25-54), around 7 percent have a disability of some kind. In this set of…
Measuring Labor Market Tightness: Data Update and New Web Feature

Measuring Labor Market Tightness: Data Update and New Web Feature

Sebastian Heise, Jeremy Pearce, and Jacob P. Weber Good measures of labor market tightness are essential to predict wage inflation and to calibrate monetary policy. In an October 2024 post,…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
Mortgage rate recovery graphic with a home, rising chart, stacked coins, and calculator

Solid Mid-Day Recovery For Rates

It’s a rarity these days, but mortgage rates actually moved lower today by more than a token amount. The average top-tier 30yr fixed rate fell to 7.54% from 7.60% yesterday. There are multiple potential factors in play when it comes to explaining the underlying bond market rally, but none of them stand out as an obvious singular motivation. For those curious, the list (which has several esoteric factors that we won’t be fully explaining here) includes, but is not limited to:
traders covering bets on higher rates ahead of tomorrow’s jobs report
concerns over European bond market contagion focused on France and Italy 
reassuring comments from Fed speakers helping Fed rate expectations move lower
technical buying opportunity when Treasury yields hit 5.34% (10yr)
A day like today invites consideration about bigger picture ceilings, but it will need to bring friends in order for that conversation to continue. We are bound to see periodic sighs of relief any time rates move higher as relentlessly as they have in the past month. Tomorrow’s jobs report is as likely as anything to set the tone for the rest of that conversation. If job growth is much stronger than expected, the conversation is over until further notice. If it’s much weaker than expected, we’ll talk.
Read More »
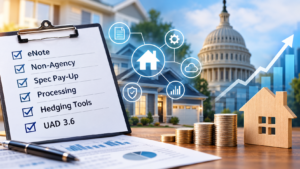
Mortgage technology checklist with eNote, non-agency lending, processing, hedging tools, UAD 3.6, home, and rising market chart

eNote, Non-Agency, Spec Pay-Up, Processing, Hedging Tools; UAD 3.6 Paused; Agency Pricing Changes

Welcome to the 4th quarter. Remember when, in 2024, the informal slogan for many in our biz was, “Stay alive ‘til ’25!”? (’27 isn’t expected to be heaven.) This is the month of Halloween. Suddenly residential lending is filled with tricks or treats, along with conferences of varying value. People are on the move: the jobs section of this Commentary has been filled with transitions and promotions. On a larger scale, the pace of company changes is picking up. Just when people are wondering if the shift into non-Agency products is becoming “long in the tooth,” New York Life Investment Management is taking majority control of Invictus Capital Partners, the company behind Verus. The asset manager has $838 billion under management, and Verus is already having its biggest securitization year yet with about $8.9 billion across 14 deals in 2026. Meanwhile, in Agency news, keeping track of 38-year-old FHFA Director Bill Pulte’s tweets, impacting thousands of lenders and millions of borrowers, has become a full-time job. “Fannie and Freddie are hereby moving to one pricing grid with VantageScore joining the existing FICO Classic pricing grid.” But wait! The FHFA and Fannie and Freddie announced (here and here) that approved lenders may apply for a temporary exception to the November 2nd, Uniform Appraisal Dataset (UAD) 3.6 appraisal delivery deadline, “a move that follows concerns MBA and its members raised with the GSEs about readiness across the broader appraisal ecosystem.” (Today’s podcast can be found here. This week’s ‘casts are presented by Gateless, intelligent automation that gives you the competitive edge. Gateless solutions reduce costs, deliver a superior borrower experience, and mitigate risk by automating tasks and decisions historically made by people. Today’s has an interview with Gateless’ Mike Brown on how AI is overcoming legacy technology and operational friction to improve risk management, accelerate time-to-close, demonstrate ROI, and ultimately enable a scalable “no-touch” underwriting experience.)

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy