


FHA nominee Matt Jones says he’ll target more housing supply and lower costs
In his Senate confirmation hearing, Jones highlighted manufactured housing, limits on large investors and new credit underwriting models

In his Senate confirmation hearing, Jones highlighted manufactured housing, limits on large investors and new credit underwriting models
The USDA and HUD agreed earlier this week to streamline environmental reviews for federally funded rural housing projects
Exclusive CMLS coverage: Former Bright MLS strategy chief David Charron urged CMLS attendees to cut friction and invest for where the industry will be 18-month
For agents, Abrams said a slower market requires a different approach to prospecting
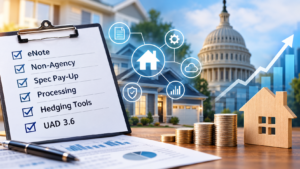
Welcome to the 4th quarter. Remember when, in 2024, the informal slogan for many in our biz was, “Stay alive ‘til ’25!”? (’27 isn’t expected to be heaven.) This is the month of Halloween. Suddenly residential lending is filled with tricks or treats, along with conferences of varying value. People are on the move: the jobs section of this Commentary has been filled with transitions and promotions. On a larger scale, the pace of company changes is picking up. Just when people are wondering if the shift into non-Agency products is becoming “long in the tooth,” New York Life Investment Management is taking majority control of Invictus Capital Partners, the company behind Verus. The asset manager has $838 billion under management, and Verus is already having its biggest securitization year yet with about $8.9 billion across 14 deals in 2026. Meanwhile, in Agency news, keeping track of 38-year-old FHFA Director Bill Pulte’s tweets, impacting thousands of lenders and millions of borrowers, has become a full-time job. “Fannie and Freddie are hereby moving to one pricing grid with VantageScore joining the existing FICO Classic pricing grid.” But wait! The FHFA and Fannie and Freddie announced (here and here) that approved lenders may apply for a temporary exception to the November 2nd, Uniform Appraisal Dataset (UAD) 3.6 appraisal delivery deadline, “a move that follows concerns MBA and its members raised with the GSEs about readiness across the broader appraisal ecosystem.” (Today’s podcast can be found here. This week’s ‘casts are presented by Gateless, intelligent automation that gives you the competitive edge. Gateless solutions reduce costs, deliver a superior borrower experience, and mitigate risk by automating tasks and decisions historically made by people. Today’s has an interview with Gateless’ Mike Brown on how AI is overcoming legacy technology and operational friction to improve risk management, accelerate time-to-close, demonstrate ROI, and ultimately enable a scalable “no-touch” underwriting experience.)

If you’re planning to rent out your home after moving, prepare the property by addressing necessary repairs, deep cleaning and removing personal belongings, researching the local rental market, checking applicable rental requirements, and setting up a plan for managing the property. Taking these steps before you leave can help ensure the home is ready for […]
The post How to Prepare Your Home for Renters Before Moving Out appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
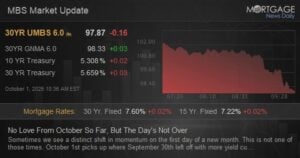
Sometimes we see a distinct shift in momentum on the first day of a new month. This is not one of those times. October 1st picks up where September 30th left off with more yield curve steepening (2yr and 10yr yield getting farther apart). This is a reflection of the sudden shift in economic data expectations last Wednesday combined with the fact that the Fed rate hike outlook has been broadly flat after Wednesday’s pop. It’s still anyone’s game as far as today goes. 10s and MBS are moderately weaker while the 2yr is almost 5bps lower (anchored to those now-resilient Fed Funds Futures). Stronger ISM components (orders, backlogs, prices) caused an initial pop in yields, but we’ve already recovered 20 minutes later.
Geoeconomic risk—the risk that firms incur valuation losses when countries deploy economic, trade, or financial leverage for geopolitical aims—has become a first-order concern for investors. In this post, based on our recent Staff Report, we document that domestic U.S. stocks expose investors to substantial geoeconomic risk through firms’ global supply-chain relationships, affecting investors’ returns and portfolio allocation. We also find that investors are compensated for bearing geoeconomic risk through higher risk premia.
A framework for disclosure, authentication and ongoing fitness in a world where the caller might not be a person at all