HELOC vs. Home Equity Loan in Tennessee: Fixed Second Mortgage or Flexible Line?
Tennessee homeowners comparing a HELOC with a home equity loan are choosing between revolving credit and a closed-end second mortgage. Both may leave the first mortgage in place, but funding, rates, payments, and future access differ. The best fit depends on when funds are needed, how predictable the payment must be, and the expected payoff period.
Here, “home equity loan” means the closed-end lump-sum option. A HELOC may also occupy second-lien position, but it is open-end revolving credit.
Quick Answer
A home equity loan may fit a known lump sum and scheduled payment, often at a fixed rate. A HELOC may fit staged expenses and allow repeated draws during the draw period. Compare the same timeline, fees, payoff date, and rate-stress assumptions, not the advertised rate alone.
HELOC vs. Home Equity Loan at a Glance
The Consumer Financial Protection Bureau explains that a home equity loan generally provides a lump sum, while a HELOC permits multiple draws from an approved credit limit.
Attribute | Closed-End Home Equity Loan | HELOC |
|---|---|---|
Access to funds | One lump sum | Multiple draws during an approved draw period |
Rate structure | Often fixed; confirm the note | Usually variable; fixed segments may be offered |
Payment | Scheduled installment payment | Changes with balance, rate, and account period |
Re-borrowing | Generally unavailable | May be available during the draw period |
Best timing | Known, one-time expense | Staged or uncertain expenses |
Main risk | Paying interest on the full balance from closing | Variable rates, payment changes, and restricted future access |
First mortgage | Generally remains in place | Generally remains in place |
Collateral | Home secures the debt | Home secures the line |
Neither structure is automatically cheaper. Use the same amount, draw timing, payoff horizon, fees, and rate assumptions; then compare monthly cash flow and total dollars paid.
How Borrowing Timing Can Change the Payment
Consider a hypothetical Middle Tennessee homeowner planning an $80,000 renovation. The contractor expects three payments: $20,000 initially, $25,000 four months later, and $35,000 in month eight.
Assume a HELOC begins at a hypothetical 8.50% variable rate and permits interest-only payments during the draw period:
Project stage | Outstanding balance | Illustrative monthly interest |
|---|---|---|
Initial draw | $20,000 | About $142 |
Second draw | $45,000 | About $319 |
Final draw | $80,000 | About $567 |
If the variable rate later increased to 10.50%, interest on an $80,000 balance would be approximately $700 per month. Actual HELOC payments may also include principal, and payments can increase when the draw period ends. The CFPB’s HELOC guidance explains that repayment-period payments may be substantially higher.
Now compare a hypothetical $80,000 closed-end home equity loan at 9.00% for 15 years. Its principal-and-interest payment would be approximately $811 per month, and the full $80,000 would begin accruing interest at closing.
These educational examples are not loan quotes or an APR comparison. First-year HELOC interest depends on draw dates and rate changes. A home equity loan starts interest on the full amount at closing but uses scheduled amortization. Compare interest and fees over the period you expect to keep the debt.
Use the mortgage payment calculator to test a proposed closed-end amount and term.
Which Option Fits Which Tennessee Homeowner?
Borrower situation | Option that may fit | Reason |
|---|---|---|
Renovation invoices will arrive over 12 months | HELOC | Funds can be drawn as project costs occur |
A contractor, debt payoff, or major expense requires a defined amount now | Home equity loan | Lump-sum funding and a scheduled payment may be easier to budget |
The amount needed is uncertain and payment flexibility matters | HELOC | Revolving access may reduce unnecessary upfront borrowing |
Income is tight or future payments would be difficult after a rate increase | Neither until reviewed | Equity alone does not establish repayment capacity |
A first-mortgage refinance or home sale may occur soon | Compare both carefully | Closing costs, early-closure provisions, payoff, and subordination may affect the result |
A HELOC is not guaranteed emergency cash. A creditor may freeze or reduce advances in circumstances permitted by federal rules and the agreement, including a significant property-value decline or a material financial change affecting repayment. Review those provisions if dependable access matters.
Qualification and Costs Can Change the Answer
Both products require more than available equity. Review the broader HELOC qualification factors and home equity loan and second-mortgage options before selecting a structure.
A lender may evaluate:
- Accepted property value and valuation method
- First-mortgage balance, other liens, and requested loan or line amount
- Combined loan-to-value or high combined loan-to-value
- Credit and mortgage-payment history
- Verified income, assets, employment, and debt-to-income ratio
- Property type, condition, and occupancy
- Use of proceeds and product-specific restrictions
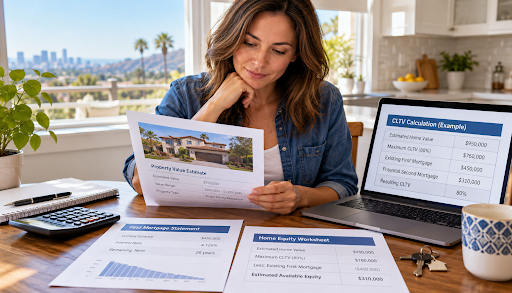
CLTV compares all mortgage balances, including the proposed loan or line, with the accepted property value. For example, a $250,000 first mortgage plus $60,000 of new financing against a $400,000 value equals 77.5% CLTV. A lender may use the full HELOC limit when calculating HCLTV. Credit score, DTI, and maximum leverage still vary by lender and program.
A home equity loan may include origination, valuation, title, recording, and other closing charges. A HELOC may include similar costs plus annual, transaction, inactivity, conversion, or early-closure charges. Some lenders waive upfront costs but recapture them if the line closes early. Review the actual disclosures instead of treating a low opening cost as a low total cost.
Before applying, ask for:
- Current rate, index, margin, floor, cap, and adjustment frequency
- Payment during the draw and repayment periods
- Estimated closing costs, annual fees, and transaction charges
- Minimum initial draw and minimum balance requirements
- Fixed-rate conversion terms, if offered
- Early-closure, payoff, and subordination provisions
- Payment under a reasonable rate-increase stress test
The blended rate calculator can help evaluate the weighted rate across the existing first mortgage and proposed home-equity financing. It does not replace a total-cost or payment comparison.
Tennessee Closing Considerations and Next Steps
Tennessee counties do not change the basic HELOC or home equity loan structure, but title, valuation, recording, insurance, lender, and closing charges can change the final cost comparison.
For many non-purchase-money loans secured by a principal residence, a federal three-business-day right of rescission may apply before funds are released. Exceptions exist, so confirm the funding date for the specific transaction.
Tennessee also imposes a recordation tax on recorded mortgage indebtedness. As of October 20, 2026, the Tennessee Department of Revenue lists the mortgage tax rate as $0.115 per $100 of indebtedness, with the first $2,000 exempt. For $80,000 of recorded indebtedness, the state tax would be about $89.70 before other recording charges. This is an educational example; the closing provider should calculate the taxable amount for the actual loan or line instrument.
Neither product is automatically better. Match the product to the funding schedule, payment tolerance, expected payoff date, and actual lender terms. Request a side-by-side Tennessee home-equity financing review using the same amount, draw schedule, payoff period, fees, and rate assumptions for both products.
Frequently Asked Questions
Is a HELOC technically a second mortgage?
When a first mortgage already exists, a HELOC is commonly recorded as a second mortgage or junior lien. “Second mortgage” in a product comparison usually refers to a closed-end home equity loan, while a HELOC is open-end revolving credit.
Does a home equity loan always have a fixed rate?
No. Many closed-end home equity loans offer fixed rates, but adjustable rates or balloon features may exist. Confirm the note, repayment term, payment schedule, fees, and payoff provisions.
Can a HELOC payment increase?
Yes. Additional draws, rate adjustments, an expiring introductory rate, or the transition to repayment can increase the payment. Test both the opening payment and a reasonable future-payment scenario.
Which option is easier to qualify for?
Neither option is universally easier. Eligibility depends on equity, CLTV or HCLTV, credit, verified income, DTI, property, occupancy, requested amount, and lender guidelines. Compare actual qualified scenarios rather than advertised features.
This article is for educational purposes and does not constitute a commitment to lend, loan approval, legal advice, tax advice, or a guarantee of rates, terms, credit limits, eligibility, property acceptance, funding, or closing. Your home secures a HELOC or home equity loan, and failure to repay may result in foreclosure and loss of the property. Programs and qualification requirements are subject to borrower, property, lender, investor, agency, and underwriting requirements.
Reviewed by
Rodney Rose
Loan Officer / Branch Manager
NMLS #1396861
DRE #00853403
E Mortgage Capital, Inc.
NMLS #1416824
WRITTEN BY
Rodney Rose
NMLS #1396861
Rodney Rose is a California mortgage professional dedicated to helping families navigate home financing with confidence. Through clear guidance on mortgage programs, loan options, and down payment assistance, Rodney Rose helps homebuyers make informed decisions and move closer to achieving their homeownership goals.
Guidance on Mortgage Payments
Loan Options & Down Payment Help
Helping Families Achive Homeownership