How Much Equity Do You Need for a Cash-Out Refinance in California?
California homeowners considering a cash-out refinance usually want two numbers: how much equity must remain and how much cash could actually reach them at closing. The answer starts with loan-to-value ratio, or LTV, but it also depends on occupancy, unit count, the lender-accepted property value, the current mortgage payoff, other liens, loan size, closing costs, credit, income, and underwriting. This article focuses on an eligible conventional cash-out refinance and explains where California high-balance and jumbo loans may change the analysis.
Quick answer. For a standard Fannie Mae cash-out refinance on a one-unit principal residence, the current maximum is generally 80% LTV. That means at least 20% equity remains after closing. This is an agency ceiling, not guaranteed approval. Other occupancies, property types, jumbo loans, and lender overlays may require more equity.
How LTV Determines the Equity You Must Keep
The Consumer Financial Protection Bureau definition of LTV compares the amount financed with the property’s appraised value. For a cash-out refinance, the planning formula is:
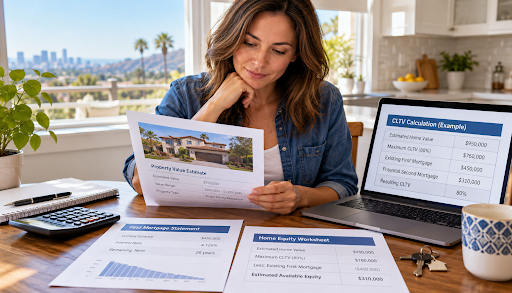
New loan amount / lender-accepted property value = LTV
As of October 22, 2026, the Fannie Mae Eligibility Matrix lists the following standard Desktop Underwriter maximums for eligible conventional cash-out refinances. These limits apply to LTV, CLTV, and HCLTV as relevant. If a junior lien remains open, the lender also evaluates the combined lien exposure. Review broader conventional loan requirements separately from this equity calculation.
Occupancy | Units | Maximum LTV | Equity Remaining |
|---|---|---|---|
Principal residence | 1 | 80% | 20% |
Principal residence | 2-4 | 75% | 25% |
Second home | 1 | 75% | 25% |
Investment property | 1 | 75% | 25% |
Investment property | 2-4 | 70% | 30% |
The implied equity is 100% minus the maximum LTV. These are agency maximums for the standard transactions shown, not a promise that every borrower or property qualifies. Manufactured homes, certain condominium reviews, and other specialized transactions can have different limits. A lender or investor may also impose a lower maximum or different pricing.
How to Calculate Estimated Cash Available
Gross equity and cash proceeds are not the same. Required equity stays in the property, while costs and payoffs use part of the available loan proceeds. Use this planning sequence:
- Maximum new loan = lender-accepted value x allowed LTV.
- Gross equity access = maximum new loan – current mortgage payoff – liens being paid.
- Estimated usable cash = gross equity access – closing costs, points, prepaid items, escrow adjustments, and required payoffs funded through the new loan.
Educational California example. Assume a one-unit principal residence, an 80% maximum LTV, no subordinate lien, a $575,000 current payoff, and $14,000 of hypothetical transaction costs paid from loan proceeds.
Accepted Value | 80% Maximum Loan | Current Payoff | Assumed Costs | Estimated Cash |
|---|---|---|---|---|
$900,000 | $720,000 | $575,000 | $14,000 | $131,000 |
$850,000 | $680,000 | $575,000 | $14,000 | $91,000 |
A $50,000 lower accepted value reduces the maximum new loan by $40,000 at 80% LTV, so estimated cash falls by the same amount when the payoff and costs stay constant. This is why an online value estimate cannot establish final proceeds. Daily payoff interest, escrow funding, lender credits, and final charges can also change the closing figure.
Why California Loan Size and Property Type Matter
California property values can push the new mortgage into high-balance conforming or jumbo territory. For 2026, the Federal Housing Finance Agency set the one-unit baseline limit at $832,750 and the high-cost ceiling at $1,249,125. The applicable limit depends on the county and unit count; the ceiling does not apply automatically to every California property.
If the proposed cash-out loan exceeds the applicable conforming limit, compare jumbo cash-out requirements. Jumbo investors set their own LTV, reserve, appraisal, credit, and proceeds rules and may require more equity than a conforming program. Condominiums, manufactured homes, multi-unit properties, and unique or high-value homes may also receive additional property review.
What Else Lenders Review Before Approval
A low LTV can strengthen a file, but equity alone does not qualify the loan. Before requesting a scenario, gather enough information to review:
- Credit history and mortgage-payment history
- Stable, documentable qualifying income and debt-to-income ratio
- Current mortgage payoff, HELOCs, second mortgages, PACE assessments, and other liens
- Assets for closing, required reserves, and post-closing liquidity
- Occupancy, unit count, property condition, title, insurance, and valuation
- How long the existing first mortgage has been open and how long a borrower has held title
For applicable Fannie Mae transactions, the cash-out refinance guidance generally requires an existing first mortgage being paid off to be at least 12 months old and at least one borrower to have held title for six months, subject to stated exceptions. It also requires six months of reserves for a Desktop Underwriter case when DTI exceeds 45%. These are Fannie Mae rules for an applicable transaction, not universal federal requirements; lenders may add overlays.
A cash-out refinance replaces the first lien, so the new rate and term apply to the full balance. If the current mortgage has favorable terms, compare a HELOC or fixed-rate second mortgage, which generally preserves the first lien but adds a separate payment, costs, and risks. Use the refinance savings calculator to compare payment, term, closing costs, and estimated break-even instead of focusing only on cash received.
Frequently Asked Questions
Does 20% equity guarantee cash-out refinance approval?
No. Twenty percent retained equity corresponds to an 80% LTV ceiling for certain standard one-unit principal-residence transactions. Approval still depends on credit, income, DTI, assets, reserves, appraisal, title, property eligibility, loan size, agency or investor rules, and lender overlays.
What if I already have a HELOC or second mortgage?
The lender will determine whether the junior lien must be paid off or may remain through subordination. A lien that remains can affect CLTV or HCLTV, while a lien paid at closing reduces net cash proceeds. The final structure must satisfy the selected program, lien-position, title, and lender requirements.
Is LTV based on an online home-value estimate?
No. An online estimate can help with early planning, but underwriting uses the value accepted under the selected program and lender process. If that value is lower than expected, the maximum loan and cash proceeds can fall. A higher value does not override program loan limits or other qualification requirements.
Can closing costs be included in the new loan?
Eligible closing costs, points, prepaid items, and certain real estate taxes may be financed in a Fannie Mae cash-out transaction, subject to the maximum loan amount and other rules. Amounts paid from the new loan reduce cash delivered to the borrower because they use part of the same LTV capacity.
Bottom Line
For many California homeowners with an eligible one-unit principal residence, 20% retained equity is the conventional starting benchmark because the standard maximum is 80% LTV. The more useful question is how much cash remains after the lender-accepted value, existing payoff, other liens, closing costs, loan limits, and qualification requirements are applied. Request a California cash-out refinance scenario review that compares estimated net proceeds, the new payment and term, closing costs, and HELOC or second-mortgage alternatives before replacing the first mortgage.
Educational disclosure. This article is for educational purposes and does not constitute a commitment to lend, loan approval, legal advice, tax advice, or a guarantee of rates, terms, eligibility, property acceptance, proceeds, or closing. Loan programs and qualification requirements are subject to borrower, property, lender, investor, agency, appraisal, title, and underwriting requirements.
Reviewed by Rodney Rose
Loan Officer / Branch Manager | NMLS #1396861 | DRE #00853403
E Mortgage Capital, Inc. | NMLS #1416824
WRITTEN BY
Rodney Rose
NMLS #1396861
Rodney Rose is a California mortgage professional dedicated to helping families navigate home financing with confidence. Through clear guidance on mortgage programs, loan options, and down payment assistance, Rodney Rose helps homebuyers make informed decisions and move closer to achieving their homeownership goals.
Guidance on Mortgage Payments
Loan Options & Down Payment Help
Helping Families Achive Homeownership