Starting Jan. 1, qualifying affordable housing rezonings can follow a 90-day Planning Commission review without a Council vote
The panel will hold a Nov. 5 hearing and could recommend her removal “for cause”
As Robbie and I prepare to head to Chicago this weekend for the “MBA National,” yesterday I was speaking with someone at the bar at Legs Inn in Northern Michigan. (Yeah, it’s somethin’.) We shouldn’t be afraid to talk about the economy, or politics, and I told her that I’ve been in capital markets for over 40 years and there are plenty of clever sayings about economics. One of them is, “The stock market is not the economy.” How good is the U.S. economy? You wouldn’t know it by stocks. Elliot F. Eisenberg, Ph.D. writes, “U.S. equity market performance is increasingly being led by the Magnificent Seven including the ‘hyperscalers’ (Amazon, Alphabet, Meta, and Microsoft) plus Apple, Nvidia, and Tesla. They have a combined market cap of almost $25 trillion, 77 percent of U.S. GDP. Moreover, Y-o-Y 26Q3 tech EPS growth is expected to be 65 percent, double the overall S&P 500. The market may be a one-trick pony, but it’s staggeringly large and profitable.” (Today’s podcast can be found here. This week’s ‘casts are presented by Floify, the mortgage industry’s leading point-of-sale platform. Dynamic Apps, which can be seen at booth 600 during MBA Annual next week, lets lenders create fully customizable loan applications for any loan type, including HELOCs, construction, agricultural lending, non-QM and more, without custom development. Today’s has an interview with Floify’s Maggie Swanson on creating fully customizable loan applications for any loan type, including HELOCs, construction, agricultural lending, non-QM, and more, without custom development.)
After yesterday’s nice comeback, here’s how we’re thinking about today. Fridays before 3-day weekends:
frequently see a move to the sidelines among certain investors. Traders who were tactically long bonds over the past 2 days could be booking profit. Translation: some of the strength over the past 2 days could turn to weakness for purely mechanical reasons.
frequently see less determination to aggressively pursue new trading ideas in the absence of compelling econ data.
often “don’t count” when it comes to forming our view of prevailing short term trends.
Bonds are starting out slightly weaker, but MBS are right in line with Wednesday’s close. Treasuries are even better than Wed’s close. It would be a victory to close around these levels today. Any improvement is a bonus. And deterioration can be forgiven, as long as it doesn’t get out of hand.
NAHB expects remodeling activity to hold steady in 2026 and grow modestly in 2027
As fall starts to show itself in cooler weather, I want to discuss a topic that usually raises temperatures: inflation. Like a budget-conscious consumer, the Federal Reserve is highly attuned to changes in the price of goods and services; minimizing such swings is one of the Fed’s primary duties, after all. But how does the Fed’s view of prices differ from that of a consumer? And how does the Fed go about stabilizing prices writ large when it lacks the ability to set prices directly? In this post, I explore that apparent paradox from the perspective of a central banker (though I remain a budget-conscious consumer when off duty).
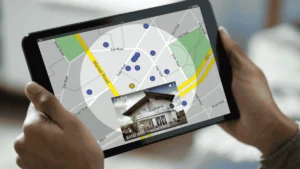
A practical build vs buy framework for mortgage leaders deciding how much tech they really want to own
Yields “Plummet” to Best Level In…
4 trading days… All the way back on October 2nd (last Friday), intraday lows were 5.151%. In other words, today’s rally was definitely nice and definitely worth discussing, but if we’re witnessing the inception of anything legitimately exciting here, it’s in an embryonic stage as of today. 10yr yields would need to be below 5.0% just over a month from now to confirm a truly big shift. As for drivers, we’d have a hard time reconciling today’s friendly reversal without giving some credit to investors “buying the dip” in bond prices (or the supportive ceiling in yields around 5.33-5.35). Additional mid-day gains followed war headlines and a decently strong 30yr bond auction. No major data tomorrow.
Market Movement Recap
01:04 PM Mid-day gains after war-related headlines. Ho-hum Treasury auction, but it would have been strong if not for the rally leading up to it. 10yr at best levels, down 5 bps at 5.622. MBS up nearly a quarter point.