

Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.4% HIKE
IMPLIED CHANGE +7.1 bps
12-MONTH OUTLOOK +83.0 bps 3-4 HIKES
TARGET BAND 3.75 - 4.00%
SOFR 3.89%
LATEST FED UPDATE 10/6/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
Do Employers Comply with Pay Transparency Requirements in Job Postings?

Do Employers Comply with Pay Transparency Requirements in Job Postings?

Richard Audoly and Roshie Xing Over the past few months, New Jersey and Vermont have joined a growing number of U.S. states in requiring employers to include an estimated salary…
A Historical Perspective on Stablecoins

A Historical Perspective on Stablecoins

Stephan Luck Digital currencies have grown rapidly in recent years. In July 2025, Congress passed the “Guiding and Establishing National Innovation for U.S. Stablecoins Act” (GENIUS) Act, establishing the first…
Calming the Panic: Investor Risk Perceptions and the Fed’s Emergency Lending During the 2023 Bank Run

Calming the Panic: Investor Risk Perceptions and the Fed’s Emergency Lending During the 2023 Bank Run

Natalia Fischl-Lanzoni, Martin Hiti, and Asani Sarkar In a companion post, we showed that during the bank run of spring 2023 investors were seemingly not concerned about bank risk broadly…
People lined up outside a bank entrance in a grand city building

Reading the Panic: How Investors Perceived Bank Risk During the 2023 Bank Run

Natalia Fischl-Lanzoni, Martin Hiti, and Asani Sarkar The bank run that started in March 2023 in the U.S. occurred at an unusually rapid pace, suggesting that depositors were surprised by…
The Financial Stability Implications of Tokenized Investment Funds

The Financial Stability Implications of Tokenized Investment Funds

Pablo Azar, Francesca Carapella, JP Perez-Sangimino, Nathan Swem, and Alexandros P. Vardoulakis In a previous post, we provided background information about the emergence of tokenized investment funds and their use…
The Emergence of Tokenized Investment Funds and Their Use Cases

The Emergence of Tokenized Investment Funds and Their Use Cases

Pablo Azar, Francesca Carapella, JP Perez-Sangimino, Nathan Swem, and Alexandros P. Vardoulakis A blockchain is a distributed database where independent computers across the world maintain identical copies of a transaction record, updating…
Financial Intermediaries and Pressures on International Capital Flows

Financial Intermediaries and Pressures on International Capital Flows

Linda S. Goldberg and Samantha Hirschhorn Global factors, like monetary policy rates from advanced economies and risk conditions, drive fluctuations in volumes of international capital flows and put pressure on…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
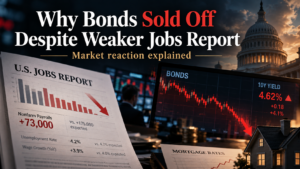
Weaker jobs report beside falling bond chart and rising Treasury yields

Why Bonds Sold Off Despite Weaker Jobs Report

Why Bonds Sold Off Despite Weaker Jobs Report

First off, read the AM commentary if you haven’t already. This recap doesn’t add much to that (but the video adds a lot). Bottom line, NFP was weaker, but that was the worst of the news. The unrounded unemployment rate barely budged and it would have moved LOWER (under 4.00%) were it not for the uptick in labor force participation. Higher oil prices contributed a bit to intraday weakness as did a recovery in French credit spreads. At the end of the day, this wasn’t the jobs report that sowed any seeds of doubt about cracks showing in the labor market.

Econ Data / Events

Average earnings mm (Sep)

0.1% vs 0.3% f’cast, 0.3% prev

Non Farm Payrolls (Sep)

29K vs 90K f’cast, 162K prev

Participation Rate (Sep)

61.8% vs — f’cast, 61.6% prev

Unemployment rate mm (Sep)

4.2% vs 4.1% f’cast, 4.1% prev

Market Movement Recap

10:06 AM Initially much stronger after NFP, but dialing back a bit. MBS up a quarter point and 10yr down 4.1bps at 4.198

02:31 PM MBS now down a quarter point and 10yr up 4bps at 5.28. Cooler heads prevail on jobs report reaction and EU credit spreads
Read More »
Higher mortgage rates reduce demand beside home loan application illustration

Higher Rates Sapped Mortgage Demand, Surprising No One

Mortgage demand shocked no one by declining last week as mortgage rates climbed to their highest level in nearly three years. The Mortgage Bankers Association (MBA) reported a 6% drop in total mortgage application volume for the week ending September 25. Both sides of the market moved lower, with the seasonally adjusted Purchase Index falling 4% and refinance applications dropping 9% . MBA said purchase and refinance activity both reached their slowest weekly pace since 2025 . Refinances always get hit hardest by rate spikes with the index now 56% lower than a year earlier. Government refinance applications fell 13% from the prior week. “Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. He noted that the 30-year fixed rate reached 7.30%, its highest level since November 2023. There was another sign that some borrowers are looking for alternatives to the traditional fixed-rate mortgage. ARM loans accounted for 10.3% of all applications, the highest share since October 2025. Kan said ARM rates were roughly 80 basis points below fixed rates, although the average 5/1 ARM rate also moved higher in the latest survey. Mortgage Rate Summary:
30yr Fixed: 7.30% (from 7.12%) | Points: 0.75 (from 0.73)
15yr Fixed: 6.56% (from 6.43%) | Points: 1.02 (from 1.15)
Jumbo 30yr: 7.27% (from 7.15%) | Points: 0.50 (from 0.53)
FHA: 6.97% (from 6.78%) | Points: 1.18 (from 0.96)
5/1 ARM: 6.47% (from 6.10%) | Points: 1.20 (from 0.76)

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy