


Fairway’s Christine Jensen on HECM reform and borrower misconceptions
Jensen offers her thoughts on the 2% upfront mortgage insurance premium, second appraisals and retirement planning use cases

Jensen offers her thoughts on the 2% upfront mortgage insurance premium, second appraisals and retirement planning use cases
Realtor.com report suggests move-up buyers will see more options and potentially softer prices, but first-time buyers will remain constrained by limited entry-level stock
Policymakers can lower frictions, but only new starter-home production changes the math
Quarterly testing can miss drift, lenders need continuous fair lending visibility
Mortgage rates are at 7.57% and demand softened more last week
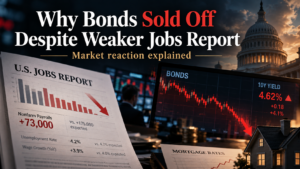
Why Bonds Sold Off Despite Weaker Jobs Report
First off, read the AM commentary if you haven’t already. This recap doesn’t add much to that (but the video adds a lot). Bottom line, NFP was weaker, but that was the worst of the news. The unrounded unemployment rate barely budged and it would have moved LOWER (under 4.00%) were it not for the uptick in labor force participation. Higher oil prices contributed a bit to intraday weakness as did a recovery in French credit spreads. At the end of the day, this wasn’t the jobs report that sowed any seeds of doubt about cracks showing in the labor market.
Econ Data / Events
Average earnings mm (Sep)
0.1% vs 0.3% f’cast, 0.3% prev
Non Farm Payrolls (Sep)
29K vs 90K f’cast, 162K prev
Participation Rate (Sep)
61.8% vs — f’cast, 61.6% prev
Unemployment rate mm (Sep)
4.2% vs 4.1% f’cast, 4.1% prev
Market Movement Recap
10:06 AM Initially much stronger after NFP, but dialing back a bit. MBS up a quarter point and 10yr down 4.1bps at 4.198
02:31 PM MBS now down a quarter point and 10yr up 4bps at 5.28. Cooler heads prevail on jobs report reaction and EU credit spreads
Leadership changes, standardized concessions, and a 12–18 month systems rollout are central to the plan
MLS legal experts at CMLS Open House urged scenario planning around cooperation, participation, and data access as lawsuits and demand letters increase
Mortgage demand shocked no one by declining last week as mortgage rates climbed to their highest level in nearly three years. The Mortgage Bankers Association (MBA) reported a 6% drop in total mortgage application volume for the week ending September 25. Both sides of the market moved lower, with the seasonally adjusted Purchase Index falling 4% and refinance applications dropping 9% . MBA said purchase and refinance activity both reached their slowest weekly pace since 2025 . Refinances always get hit hardest by rate spikes with the index now 56% lower than a year earlier. Government refinance applications fell 13% from the prior week. “Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. He noted that the 30-year fixed rate reached 7.30%, its highest level since November 2023. There was another sign that some borrowers are looking for alternatives to the traditional fixed-rate mortgage. ARM loans accounted for 10.3% of all applications, the highest share since October 2025. Kan said ARM rates were roughly 80 basis points below fixed rates, although the average 5/1 ARM rate also moved higher in the latest survey. Mortgage Rate Summary:
30yr Fixed: 7.30% (from 7.12%) | Points: 0.75 (from 0.73)
15yr Fixed: 6.56% (from 6.43%) | Points: 1.02 (from 1.15)
Jumbo 30yr: 7.27% (from 7.15%) | Points: 0.50 (from 0.53)
FHA: 6.97% (from 6.78%) | Points: 1.18 (from 0.96)
5/1 ARM: 6.47% (from 6.10%) | Points: 1.20 (from 0.76)