


Pennymac deploys VantageScore 4.0 across all production channels
The move follows FHFA and HUD guidance that opened conventional and FHA lending to competing credit score models

The move follows FHFA and HUD guidance that opened conventional and FHA lending to competing credit score models
He joined after the August close that created Real REMAX Group, with both brands keeping separate identities

A drone does not care what a house costs, how recently the kitchen was renovated, or whether the listing copy calls the backyard “an entertainer’s dream.” It doesn’t matter if you’re selling a single-family home in Cincinnati or a massive house in Houston, the drone sees the place as it is: roof, driveway, fence line, […]
The post The Best Time of Day for Real Estate Photos: Scheduling Your Drone Shoot appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.

Few architectural styles have proven as enduring or as visually commanding as the neoclassical house style. Rooted in the grandeur of ancient Greek and Roman design, neoclassical houses are defined by their formal symmetry, stately columns, and a sense of proportion that feels both timeless and intentional. Whether found in an established Southern neighborhood or […]
The post What Is a Neoclassical House Style? Key Characteristics and Design Elements appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
Today brings us the MBA of the Carolinas conference, where demographics, technology, and “building a team” are on the agenda. Here at the Michigan Mortgage Lender’s Association conference in Ypsilanti, tech is certainly “on the serving platter” in the sessions, but so is how originators should best use what they have to their advantage, which includes knowledge. For example, here’s something simultaneously sobering and hopeful for lenders. Per the Census Bureau, in 2024, 58 percent of men and 56 percent of women ages 18 to 34 lived with their parents. About 2.6 million U.S. parents provided $26.6 billion in financial support to 3.7 million children. (So you don’t have to break out the calculator, that’s about $7,200 per kid.) Think of all those potential home buyers! (Today’s podcast can be found here. This week’s ‘casts are presented by Floify, the mortgage industry’s leading point-of-sale platform. Dynamic Apps, which can be seen at booth 600 during MBA Annual next week, lets lenders create fully customizable loan applications for any loan type, including HELOCs, construction, agricultural lending, non-QM and more, without custom development. Today’s has an interview Mortgage Education Institute’s Andrew Conner on helping loan officers and small-to-midsize mortgage companies turn required continuing education and compliance from a burdensome, reactive “check-the-box” exercise into engaging, practical training and proactive support.) Lender and Brokers Products, Services, and Software

Palm-lined driveways, resort-style estates, and year-round California sunshine – Rancho Santa Fe, CA is about as close to a private paradise as Southern California gets. NFL quarterback Russell Wilson and his wife, Grammy-winning artist Ciara, certainly thought so, spending years transforming their nine-acre compound, nicknamed Amor Estate, in the area’s ultra-exclusive Del Rayo Estates into […]
The post What It Really Costs to Live in Russell Wilson’s Neighborhood appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
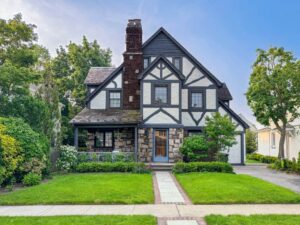

Tudor-style homes have a devoted following for good reason – their storybook charm, rich architectural details, and sense of permanence are hard to find in newer construction. Knowing how to increase the resale value of a Tudor-style house, though, takes more than a fresh coat of paint. It requires a careful balance of preservation and […]
The post How to Increase the Resale Value of a Tudor-Style House appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
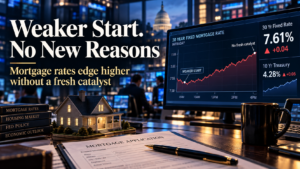
Another week begins with the frustrating reality of the bond market selling just because there’s no reason to buy. To be fair, 2yr yields are unchanged, but longer-dated yields are several bps higher than Friday afternoon. All this despite oil prices being lower and econ data being in line with expectations. At this point, anyone offering rationale for the movement is forced to craft a narrative that fits that movement. In other words, if yields were plummeting, the average bond analyst wouldn’t be harping on a laundry list of reasons that bonds are making the incorrect move.
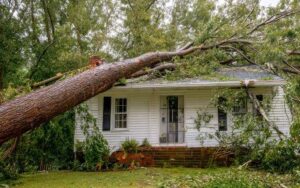
In an April post, using millions of homeowners’ insurance contracts matched with property-level exposure and disaster risk, we showed that although households are insured, they are still “on the hook” because deductibles and coverage limits leave homeowners responsible for part of a loss. Because insurers cannot perfectly observe how well homeowners maintain or protect their properties (a problem known as “moral hazard”), contract terms such as deductibles can play an important role in balancing risk sharing and incentives. By requiring homeowners to bear part of a loss, insurers can preserve incentives for policyholders to take actions that reduce damage risk. In this post, we quantify the cost of keeping homeowners on the hook. How costly is moral hazard in homeowner’s insurance? How much risk must households retain to preserve these incentives? And, importantly, who ultimately bears that residual risk? The short answer is that keeping homeowners on the hook costs insurers relatively little, but it leaves households with substantial risk, especially those least able to absorb a large loss.