


Vishal Garg lays out Better 2.0 plan during shareholder call
Daniel Lewis was removed as interim CEO effective Oct. 5, per an SEC filing

Daniel Lewis was removed as interim CEO effective Oct. 5, per an SEC filing
As credit card and HELOC balances grow, reverse mortgages and their voluntary payment structures should be considered
The Timberline Homes acquisition, Champion Homes’ third acquisition since 2025, signals a growing emphasis on direct-to-consumer sales
Industry leaders weigh in as CRMLS seeks to stop Compass from challenging MLS rules in court
Planned tech development is expected to bring even more buyers to upper New York

These last-minute moving day reminders will help you keep all the details organized when moving to a new home.
The post 8 Last-Minute Moving Day Reminders for a Stress-Free Move appeared first on Redfin | Real Estate Tips for Home Buying, Selling & More.
Today Was “Nice” For Bonds
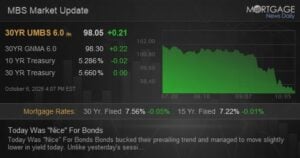
Bonds bucked their prevailing trend and managed to move slightly lower in yield today. Unlike yesterday’s session which had no clear correlation with underlying events, today’s move traced a drop in oil prices fairly clearly. Some analysts thought that an improvement in French government bonds may have been mildly encouraging as well, but that would require drawing the opposite conclusions from last week’s narrative about French bond turmoil benefiting the U.S. as a safer haven. In any event, the rally was too small to merit that much thought. Yields encountered resistance at 5.26%, but could also be broadly finding buying support when yields crest 5.3%. Bottom line, today was “nice,” but in and of itself, not enough to suggest a meaningful shift in momentum.
Market Movement Recap
02:57 PM Near best levels. MBS up over a quarter point and 10yr down 3.8bps at 5.269
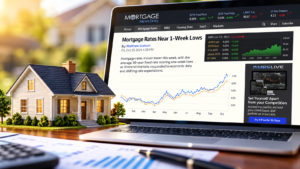
Mortgage rates actually fell today–something they’ve done only 7 times since August 25th. While the outright levels remain near the highest since 2003, they’re near the lowest in just over a week with top-tier 30yr fixed rates down to 7.56% for the average lender. What gives? Is this a sign that recent upward momentum is starting to wane? It’s too soon to conclude such things, but it is somewhat encouraging that yesterday’s long-term high was basically right in line with the high seen on September 30th (7.61 vs 7.60). This is the sort of “double top” behavior that some analysts look for when trying to identify momentum shifts. Bottom line: it’s too soon to start celebrating. But it’s better than the average day of late. [thirtyyearmortgagerates]
Lender will obtain both FICO and VantageScore on every credit pull