Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.4% HIKE
IMPLIED CHANGE +7.1 bps
12-MONTH OUTLOOK +81.7 bps 3 or 4 hikes
TARGET BAND 3.75 - 4.00%
SOFR 3.87%
LATEST FED UPDATE 10/5/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
Disability in the Labor Market: Employment and Participation

Disability in the Labor Market: Employment and Participation

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy Among people in prime working age (25-54), around 7 percent have a disability of some kind. In this set of…
Measuring Labor Market Tightness: Data Update and New Web Feature

Measuring Labor Market Tightness: Data Update and New Web Feature

Sebastian Heise, Jeremy Pearce, and Jacob P. Weber Good measures of labor market tightness are essential to predict wage inflation and to calibrate monetary policy. In an October 2024 post,…
What Is a Carbon Tariff and Why Is the EU Imposing One?

What Is a Carbon Tariff and Why Is the EU Imposing One?

Pierre Coster, Julian di Giovanni, and Isabelle Mejean The European Union has been an early adopter of carbon policies, with the introduction of the EU Emissions Trading System (ETS) in…
What Can Undermine a Carbon Tax?

What Can Undermine a Carbon Tax?

Pierre Coster, Julian di Giovanni, and Isabelle Mejean Several countries have implemented a carbon tax or cap-and-trade system to establish high carbon prices and create a disincentive for the use…
Which Entrepreneurs Boost Productivity?  

Which Entrepreneurs Boost Productivity?  

Ufuk Akcigit, Harun Alp, Jeremy Pearce, and Marta Prato Why do some entrepreneurs drive economic growth while others do not? This piece discusses new work that studies entrepreneurs using a…
Tariffs, Trade, and Tumbling Credit Scores: The Top 5 LSE Posts of 2025

Tariffs, Trade, and Tumbling Credit Scores: The Top 5 LSE Posts of 2025

Maureen Egan Each year brings a new set of economic challenges: In 2025, major areas of focus included tariffs and trade tensions, as well as the financial pressures facing younger…
A New Public Data Source: Call Reports from 1959 to 2025

A New Public Data Source: Call Reports from 1959 to 2025

Sergio Correia, Tiffany Fermin, Stephan Luck, and Emil Verner Call Reports are regulatory filings in which commercial banks report their assets, liabilities, income, and other information. They are one of…
Business professionals shaking hands across a desk during a meeting with a laptop

Letters of Recommendation in the PhD Job Market: Lessons from Specialized Banks

Kristian S. Blickle and Cecilia Parlatore Banks must extract useful signals of a potential borrower’s quality from a large set of possibly informative characteristics when making lending decisions. A model…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
Navigating Geoeconomic Risk in the U.S. Stock Market

Navigating Geoeconomic Risk in the U.S. Stock Market

Geoeconomic risk—the risk that firms incur valuation losses when countries deploy economic, trade, or financial leverage for geopolitical aims—has become a first-order concern for investors. In this post, based on our recent Staff Report, we document that domestic U.S. stocks expose investors to substantial geoeconomic risk through firms’ global supply-chain relationships, affecting investors’ returns and portfolio allocation. We also find that investors are compensated for bearing geoeconomic risk through higher risk premia.

Read More »
Bond market news graphic showing Treasury yields, laptop market chart, and U.S. Capitol backdrop

Just Another Bad Day For Bonds Without New Justification

Just Another Bad Day For Bonds Without New Justification

10yr yields hit another long-term high today, breaking above 5.30% briefly before settling just under 5.29%. There was a flash of hope after the 8:30am econ data, but that reversed fairly quickly. Reasons can be debated. Some would say today’s broadly stronger econ data supported it while pointing out that the “beat” in PCE wasn’t really news in light of the methodology changes. On that note, some might say methodology that drops core PCE by 0.361 (July vs July unrounded) means that Fed policy will be less aggressive in fighting inflation than it otherwise would have been. In that context, today’s heavy underperformance in the long end of the curve actually makes good sense, but it’s just an interesting theory to entertain. Month/Quarter-end compulsory trading could certainly be an ingredient, but there’s no great way to confirm that until several days in the future. Either way, inbound econ data certainly matters on Thu/Fri and the radar perpetually awaits any big blips shaped like Iran war truces (or escalations).

Econ Data / Events

ADP jobs (Sep)

90K vs 70K f’cast, 38K prev

Core PCE (m/m) (Aug)

0.2% vs 0.3% f’cast, 0.2% prev

Core PCE (y/y) (Aug)

3.0% vs 3.3% f’cast, 3.3% prev

Core PCE Prices QoQQ2

3.30% vs 3.6% f’cast, 4.4% prev

Corporate profitsQ2

7.7% vs 8.2% f’cast, 0.5% prev

GDPQ2

2.2% vs 1.5% f’cast, 2.1% prev

GDP Final SalesQ2

2.8% vs 2.2% f’cast, 1.9% prev

PCE (y/y) (Aug)

3.4% vs 3.7% f’cast, 3.7% prev

PCE prices (m/m) (Aug)

0.3% vs 0.4% f’cast, 0.2% prev

Market Movement Recap

10:36 AM MBS down 2 ticks (.06) on the day and a quarter point from highs. 10yr up 2.4bps at 5.269

02:19 PM MBS down a quarter point and 10yr up 5.4bps at 5.299

Read More »
Mortgage Rates End Day Higher Despite Promising Start

Mortgage Rates End Day Higher Despite Promising Start

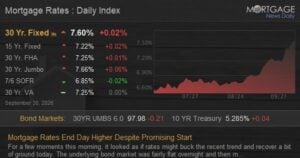
For a few moments this morning, it looked as if rates might buck the recent trend and recover a bit of ground today. The underlying bond market was fairly flat overnight and then managed to improve after this morning’s PCE inflation data. But that improvement was short-lived.  Top tier 30yr fixed rates jumped to 7.60%. That’s only 0.02% higher than yesterday, but yet another long-term high. As frustrating as it continues to be, there are no convenient scapegoats for the reversal in terms of intraday news/data. Some small case could be made that the day’s economic data wasn’t exactly rate-friendly, but the timing of the market movement and indicators elsewhere in the market suggest that’s a waste of time. The only irrefutable way to connect cause and effect is to use broad strokes. The bond market is in the midst of a fairly rapid reassessment of the outlooks for Fed policy, inflation, and the supply/demand equation for government debt. Today may have seen some additional volatility due to the mechanics of the month/quarter-end trading environment, but not to the extent that anyone should expect rates to magically fall just because tomorrow is a new month.  A meaningful drop in rates will require one or more of these things:
Iran war ending and fuel prices dropping
economic data weakening
inflation falling significantly and sustainably
There are other things that can help/hurt, but these are the big three at the moment. [thirtyyearmortgagerates]

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy