

Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.4% HIKE
IMPLIED CHANGE +7.1 bps
12-MONTH OUTLOOK +81.7 bps 3 or 4 hikes
TARGET BAND 3.75 - 4.00%
SOFR 3.87%
LATEST FED UPDATE 10/5/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
Disability in the Labor Market: Employment and Participation

Disability in the Labor Market: Employment and Participation

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy Among people in prime working age (25-54), around 7 percent have a disability of some kind. In this set of…
Measuring Labor Market Tightness: Data Update and New Web Feature

Measuring Labor Market Tightness: Data Update and New Web Feature

Sebastian Heise, Jeremy Pearce, and Jacob P. Weber Good measures of labor market tightness are essential to predict wage inflation and to calibrate monetary policy. In an October 2024 post,…
What Is a Carbon Tariff and Why Is the EU Imposing One?

What Is a Carbon Tariff and Why Is the EU Imposing One?

Pierre Coster, Julian di Giovanni, and Isabelle Mejean The European Union has been an early adopter of carbon policies, with the introduction of the EU Emissions Trading System (ETS) in…
What Can Undermine a Carbon Tax?

What Can Undermine a Carbon Tax?

Pierre Coster, Julian di Giovanni, and Isabelle Mejean Several countries have implemented a carbon tax or cap-and-trade system to establish high carbon prices and create a disincentive for the use…
Which Entrepreneurs Boost Productivity?  

Which Entrepreneurs Boost Productivity?  

Ufuk Akcigit, Harun Alp, Jeremy Pearce, and Marta Prato Why do some entrepreneurs drive economic growth while others do not? This piece discusses new work that studies entrepreneurs using a…
Tariffs, Trade, and Tumbling Credit Scores: The Top 5 LSE Posts of 2025

Tariffs, Trade, and Tumbling Credit Scores: The Top 5 LSE Posts of 2025

Maureen Egan Each year brings a new set of economic challenges: In 2025, major areas of focus included tariffs and trade tensions, as well as the financial pressures facing younger…
A New Public Data Source: Call Reports from 1959 to 2025

A New Public Data Source: Call Reports from 1959 to 2025

Sergio Correia, Tiffany Fermin, Stephan Luck, and Emil Verner Call Reports are regulatory filings in which commercial banks report their assets, liabilities, income, and other information. They are one of…
Business professionals shaking hands across a desk during a meeting with a laptop

Letters of Recommendation in the PhD Job Market: Lessons from Specialized Banks

Kristian S. Blickle and Cecilia Parlatore Banks must extract useful signals of a potential borrower’s quality from a large set of possibly informative characteristics when making lending decisions. A model…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
Do Employers Comply with Pay Transparency Requirements in Job Postings?

Do Employers Comply with Pay Transparency Requirements in Job Postings?

Over the past few months, New Jersey and Vermont have joined a growing number of U.S. states in requiring employers to include an estimated salary range in their online job listings. Has this push for greater pay transparency been effective? In this post, we use granular data on U.S. job postings from Lightcast to assess employers’ compliance with these new regulations. Focusing on the jurisdictions that adopted pay transparency laws early on, we find that many employers ignore pay transparency requirements; roughly a quarter of job listings covered by these laws fail to include salary information.
Read More »
A Historical Perspective on Stablecoins

A Historical Perspective on Stablecoins

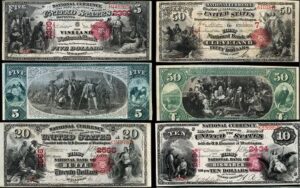
Digital currencies have grown rapidly in recent years. In July 2025, Congress passed the “Guiding and Establishing National Innovation for U.S. Stablecoins Act” (GENIUS) Act, establishing the first comprehensive federal framework governing the issuance of stablecoins. In this post, we place stablecoins in a historical perspective by comparing them to national bank notes, a form of privately issued money that circulated in the United States from 1863 through 1935.

Read More »
Calming the Panic: Investor Risk Perceptions and the Fed’s Emergency Lending During the 2023 Bank Run

Calming the Panic: Investor Risk Perceptions and the Fed’s Emergency Lending During the 2023 Bank Run

In a companion post, we showed that during the bank run of spring 2023 investors were seemingly not concerned about bank risk broadly but rather became sensitized to the risk of only about a third of all publicly traded banks. In this post, we investigate how the Federal Reserve’s liquidity support affected investor risk perceptions during the run. We find that the announcement of the Fed’s novel Bank Term Funding Program (BTFP), and subsequent borrowings from the program, substantially reduced investor risk perceptions. However, borrowings from the Fed’s traditional discount window (DW) had no such effect.

Read More »
People lined up outside a bank entrance in a grand city building

Reading the Panic: How Investors Perceived Bank Risk During the 2023 Bank Run

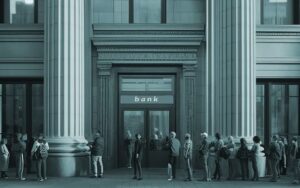
The bank run that started in March 2023 in the U.S. occurred at an unusually rapid pace, suggesting that depositors were surprised by these events. Given that public data revealed bank vulnerabilities as early as 2022:Q1, were other market participants also surprised? In this post, based on a recent paper, we develop a new, high-frequency measure of bank balance sheet risk to examine how stock market investors’ risk sensitivity evolved around the run. We find that stock market investors only became attentive to bank risk after the run and only to the risk of a limited number (less than one-third) of publicly traded banks. Surprisingly, investors seem to have mostly focused on media exposure and not fundamentals when evaluating bank risk. In a companion post, we examine how the Federal Reserve’s liquidity support affected investor risk perceptions.

Read More »
The Financial Stability Implications of Tokenized Investment Funds

The Financial Stability Implications of Tokenized Investment Funds

In a previous post, we provided background information about the emergence of tokenized investment funds and their use cases. These use cases are currently limited to the digital asset ecosystem. However, the recent approval of cryptocurrency exchange-traded funds (ETFs) and the passage of the GENIUS Act raise concerns about the impact of these tokenized investment fund to the broader financial system. In this post, we assess this impact by considering three economic mechanisms based in part on market participants’ investment strategies and liquidity needs. They include: liquidity transformation, interconnections between the digital asset and the traditional financial system, and transaction settlement. Through these mechanisms, tokenization of investment funds can bring about financial stability benefits in the form of reduced redemption pressures and additional sources of liquidity for fund issuances, but may also increase interconnectedness between the traditional financial system and digital asset ecosystem, thereby amplifying existing financial stability risks.

Read More »
The Emergence of Tokenized Investment Funds and Their Use Cases

The Emergence of Tokenized Investment Funds and Their Use Cases

A blockchain is a distributed database where independent computers across the world maintain identical copies of a transaction record, updating it only when the network reaches consensus on new transactions—making the history transparent and extraordinarily difficult to alter. Historically, bonds have traded almost entirely in over-the-counter (OTC) markets, while equities and money market fund shares have largely settled through centralized infrastructures such as stock exchanges and central securities depositories. In both settings, each institution maintains its own records, and post-trade steps like confirmation, clearing, and settlement require multiple intermediaries and repeated reconciliation.

Read More »
Financial Intermediaries and Pressures on International Capital Flows

Financial Intermediaries and Pressures on International Capital Flows

Global factors, like monetary policy rates from advanced economies and risk conditions, drive fluctuations in volumes of international capital flows and put pressure on exchange rates. The components of international capital flows that are described as global liquidity—consisting of cross-border bank lending and financing of issuance of international debt securities—have sensitivities to risk conditions that have evolved considerably over time. This risk sensitivity has been driven, in part, by the composition and business models of the financial institutions involved in funding.  In this post, we ask whether these same features have led to changes in the pressures on currency values as risk conditions evolve. Using the Goldberg and Krogstrup (2023) Exchange Market Pressure (EMP) country indices, we show that the features of financial institutions in the source countries for international capital do influence how destination countries experience currency pressures when risk conditions change. Better shock-absorbing capacity in financial institutions moderates the pressures toward depreciation of currencies during adverse global risk events.  

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy