

Hands stacking coins to illustrate saving, budgeting, or building financial growth

Mortgage Rate Intelligence & Market Updates

Stay informed about economic developments that may influence mortgage rates and home financing decisions. Explore updates covering inflation, Federal Reserve policy, Treasury yields, housing trends, and other important market indicators. Use the category filters to browse relevant economic and mortgage news, then select an article to read the full update. Review the latest stories and market insights to better understand changing conditions when considering your mortgage options.
RATE WATCH
FED FUNDS RATE 3.88%
NEXT FOMC 10/28/2026
NEXT MOVE 28.4% HIKE
IMPLIED CHANGE +7.1 bps
12-MONTH OUTLOOK +83.0 bps 3-4 HIKES
TARGET BAND 3.75 - 4.00%
SOFR 3.89%
LATEST FED UPDATE 10/6/2026

What Today’s Economic Data Can Mean for Mortgage Rates

Mortgage rates can respond to changes in inflation, employment, Federal Reserve policy, Treasury yields, and expectations about future economic growth. These factors do not determine mortgage rates by themselves, but they can influence the broader bond market and the pricing lenders offer.

For homebuyers and homeowners, the important question is not simply whether economic news is “good” or “bad.” The key is how new information changes expectations for inflation, interest rates, and the economy. Those changes can contribute to mortgage rate movement and affect purchasing power, refinance opportunities, and monthly payment estimates.

Use the market updates below as supporting information, then consider your specific loan type, credit profile, property, and financing goals when evaluating current mortgage options.

Economic News Hub

Real Estate & Financial Market Updates

Article
Does the Phillips Curve Steepen When Costs Surge?

Does the Phillips Curve Steepen When Costs Surge?

Simone Lenzu Inflation does not always respond to cost and demand pressures in the same way. When shocks are small, the mapping from costs to prices is roughly proportional—double the…
Anatomy (not Autopsy) of the Phillips Curve

Anatomy (not Autopsy) of the Phillips Curve

Simone Lenzu The relationship between inflation and real economic activity has long been central to debates in macroeconomics and monetary policy. At the core of this debate is the Phillips…
New York Fed EHIs Reveal Small Business Struggles

New York Fed EHIs Reveal Small Business Struggles

Will Aarons and Asani Sarkar The New York Fed’s Economic Heterogeneity Indicators (EHIs) aim to study macroeconomic outcomes experienced by various groups of people and businesses. We recently added a suite of indicators describing the performance…
A New Dataset for Consumer Spending in the New York Fed EHIs

A New Dataset for Consumer Spending in the New York Fed EHIs

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy We are enhancing our set of Economic Heterogeneity Indicators (EHIs) by adding a set of metrics on consumer spending with…
Understating Rising Quality Means Import Price Inflation Is Overstated

Understating Rising Quality Means Import Price Inflation Is Overstated

Danial Lashkari It is common for price measures to consider changes in quality. That is, a price index might fall even though listed prices are unchanged because the quality of…
Disability in the Labor Market: Earnings

Disability in the Labor Market: Earnings

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy In our previous post we learned that, in general, people with disabilities participate in the labor market at significantly lower…
Disability in the Labor Market: Employment and Participation

Disability in the Labor Market: Employment and Participation

Rajashri Chakrabarti, Thu Pham, Beck Pierce, and Maxim L. Pinkovskiy Among people in prime working age (25-54), around 7 percent have a disability of some kind. In this set of…
Measuring Labor Market Tightness: Data Update and New Web Feature

Measuring Labor Market Tightness: Data Update and New Web Feature

Sebastian Heise, Jeremy Pearce, and Jacob P. Weber Good measures of labor market tightness are essential to predict wage inflation and to calibrate monetary policy. In an October 2024 post,…
Rodney Rose Mortgage Team
Loans available nationwide
Low Rate, Low Fee.
"A Loan for every home"
Guaranteed Closing*
Rodney Rose, Loan Officer and Branch Manager
Rodney Rose
Loan Officer / Branch Manager
NMLS#: 1396861 DRE#: 00853403
C: (916) 232 3040
E: rrose@emortgagecapital.com
W: MortgageMarketUpdate.com
Better Business Bureau accreditation badge on a white background
Offices
Effect of Tariffs on U.S. Small Businesses

Effect of Tariffs on U.S. Small Businesses

How has the recent implementation of tariffs affected small businesses? Due to lack of data, little is known about this issue. In this Liberty Street Economics post, we use data from the 2025 edition of the Small Business Credit Survey (SBCS) to explore this question for businesses nationally and in the Second District (defined, for the purpose of this study, as New York, New Jersey, and Connecticut). We find that the majority of national firms in the goods and retail sectors reported experiencing financial challenges due to tariffs in 2025, with even larger shares of regional firms doing so. In response, about 80 percent of national and regional firms passed on at least some of the higher costs of imported inputs to customers, while about 60 percent absorbed some of the costs, as many firms did some of both. Firms that faced greater tariff challenges in 2025 were more pessimistic about employment and revenues in 2026.
Read More »
More Tariff Pass‑Through Is in the Pipeline

More Tariff Pass‑Through Is in the Pipeline

The past year brought dramatic changes to U.S. trade policy, including sweeping new tariffs, as well as a Supreme Court decision that further reshaped the tariff landscape. Many businesses saw their costs increase significantly and faced complex decisions about whether to absorb the tariffs through lower profit margins, raise their prices to recover the higher costs, or some combination of the two. Last year, we found that most businesses had passed on at least some of these higher costs to their customers through higher prices. Now, over a year later, have businesses finished adjusting prices, or do further tariff-induced price increases lie ahead? Our latest regional business surveys reveal that nearly half of firms that have paid tariffs still plan additional price increases to offset these costs, with some expecting to raise prices six months or more in the future.

Read More »
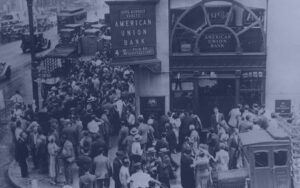
What Do Over 3,000 Bank Runs Teach Us About Banking Crises?

What Do Over 3,000 Bank Runs Teach Us About Banking Crises?

Runs on financial institutions are one of the salient markers of financial crises. But the role of runs in crises is a topic of longstanding debate. Runs can be seen as the key turning point, whereby even small shocks can generate severe crises with widespread bank failures. Another view is that runs are mainly a symptom of deeper rot in the financial system, exacerbating crises rather than being their primary cause. Understanding this debate has first order implications for how to think about financial crises and the appropriate policy responses. In this post, we use a new database of more than 3,000 bank runs (introduced in our companion post) to show that poor fundamentals are central to explaining both when runs occur and when they have severe economic effects. We argue that this evidence tempers the view that small shocks can have outsized real effects through self-fulfilling run dynamics.

Read More »
Using AI to Let History Speak About Bank Runs

Using AI to Let History Speak About Bank Runs

Banking crises are commonly associated with bank runs and banking panics, yet our empirical understanding of bank runs is constrained by a lack of bank-level data. In a new paper, we use large language models (LLMs) to extract information on bank runs from millions of digitized historical newspaper pages, creating the most comprehensive database of bank runs in U.S. history. Every bank run episode that we identify is documented on a companion website where users can browse and examine individual episodes, and read the original newspaper articles. In this post, we describe how we built this dataset and discuss what its basic features reveal.

Read More »
The Disappearing Overnight Drift

The Disappearing Overnight Drift

In a 2021 Liberty Street Economics post, we documented the “overnight drift”—a large, persistent return to holding U.S. equity futures in the narrow window between 2:00 and 3:00 a.m. Eastern time, when European equity markets open. Five additional years of data later, that pattern appears to have faded: the 2:00–3:00 window that previously generated roughly 3.7 percent per annum has averaged close to zero since 2021. In this post, we revisit the overnight drift in light of the post-publication sample and use our inventory-risk framework to ask which of three observable channels—the dispersion of closing order imbalances, the level of return variance, or the risk-bearing capacity of liquidity providers—accounts for the change.

Read More »
Liquidity Fades as Treasuries Age

Liquidity Fades as Treasuries Age

More than $30 trillion U.S. Treasury debt is outstanding. Less than 4 percent of this amount, which is associated with the most recently issued Treasuries, called on-the-run securities, accounts for 65 percent of average daily trading volume. The remaining portion of the amount outstanding is accounted for by seasoned issues that have been replaced by newer benchmarks, which are referred to as off-the-run securities. In this post, we review the key results in our paper that uses transaction-level Treasury TRACE data to study how trading activity and liquidity evolve as securities move from on-the-run to off-the-run. We show three main patterns. First, off-the-run notes and bonds rely much more on dealer-to-customer intermediation than benchmark securities. Second, trading activity falls sharply and transaction costs increase as securities age. Third, securities that are cheapest to deliver into Treasury futures are an important exception: they trade more actively than other off-the-run bonds of similar age.

Read More »
How Resilient Were Emerging Market Economies Through the 2022‑23 U.S. Monetary Tightening Cycle?

How Resilient Were Emerging Market Economies Through the 2022‑23 U.S. Monetary Tightening Cycle?

The cross-border spillover effects of shifts in U.S. monetary policy have long been a focus of academics and policymakers alike. A common finding in the literature is that changes in the stance of U.S. monetary policy have sizable effects on economic activity and financial markets in emerging market economies (EMEs). In this post, we analyze one specific aspect of these spillovers: how EMEs fared through the U.S. monetary policy tightening cycle of 2022-23 relative to the predictions of a model, which was calibrated to capture empirically relevant features of these economies based on historical data. We find that more vulnerable EMEs fared better in both financial market and growth outcomes than would be expected from our model, while the relatively less vulnerable fared a bit better than the model predictions for financial outcomes but substantially worse for growth outcomes.

Read More »
The Post‑COVID Decline in the Labor Share

The Post‑COVID Decline in the Labor Share

The labor share of income in the U.S. is currently at its lowest-ever level in the post-war period. The labor share measures the fraction of economic output paid to workers as wages and salaries. As such, it is a useful benchmark for wage growth: when the labor share falls, it means that productivity, prices, or both are growing faster than wages. After much-studied drops in the 2000s, the labor share fell sharply again after the COVID pandemic. In this post, we compare the dynamics of the labor share post-COVID to earlier periods to understand whether the recent decline represents the continuation of a trend or a new and distinct phenomenon. We find that both the cyclicality of the labor share and the contribution of reallocation to the labor share post-COVID are similar to earlier periods.

Read More »
Synthetic Stablecoins and Financial Stability

Synthetic Stablecoins and Financial Stability

On October 10, 2025, the announcement of a potential additional 100 percent tariff on Chinese goods drove risk-off moves across equities, Treasuries, credit spreads, and digital assets. Digital asset prices fell sharply, trading volumes surged, and liquidity vanished from key exchanges. In this post, we show how the price shock in digital assets was transmitted and amplified through a class of instruments called synthetic stablecoins—crypto assets whose structural design turned an external shock into a self-reinforcing deleveraging spiral within the crypto ecosystem.

Read More »
By using our site, you agree to use our cookies. For more information, read our Privacy Policy